Asset and equipment finance
Finance the equipment without draining the cash that runs the business.
Trucks, vans, machinery, fit-out, medical and IT equipment. We match the structure to the asset and to your accountant's view on GST and tax, then find the lender whose policy fits.
An enquiry is not an application. No deposit or documents are needed to start the conversation.
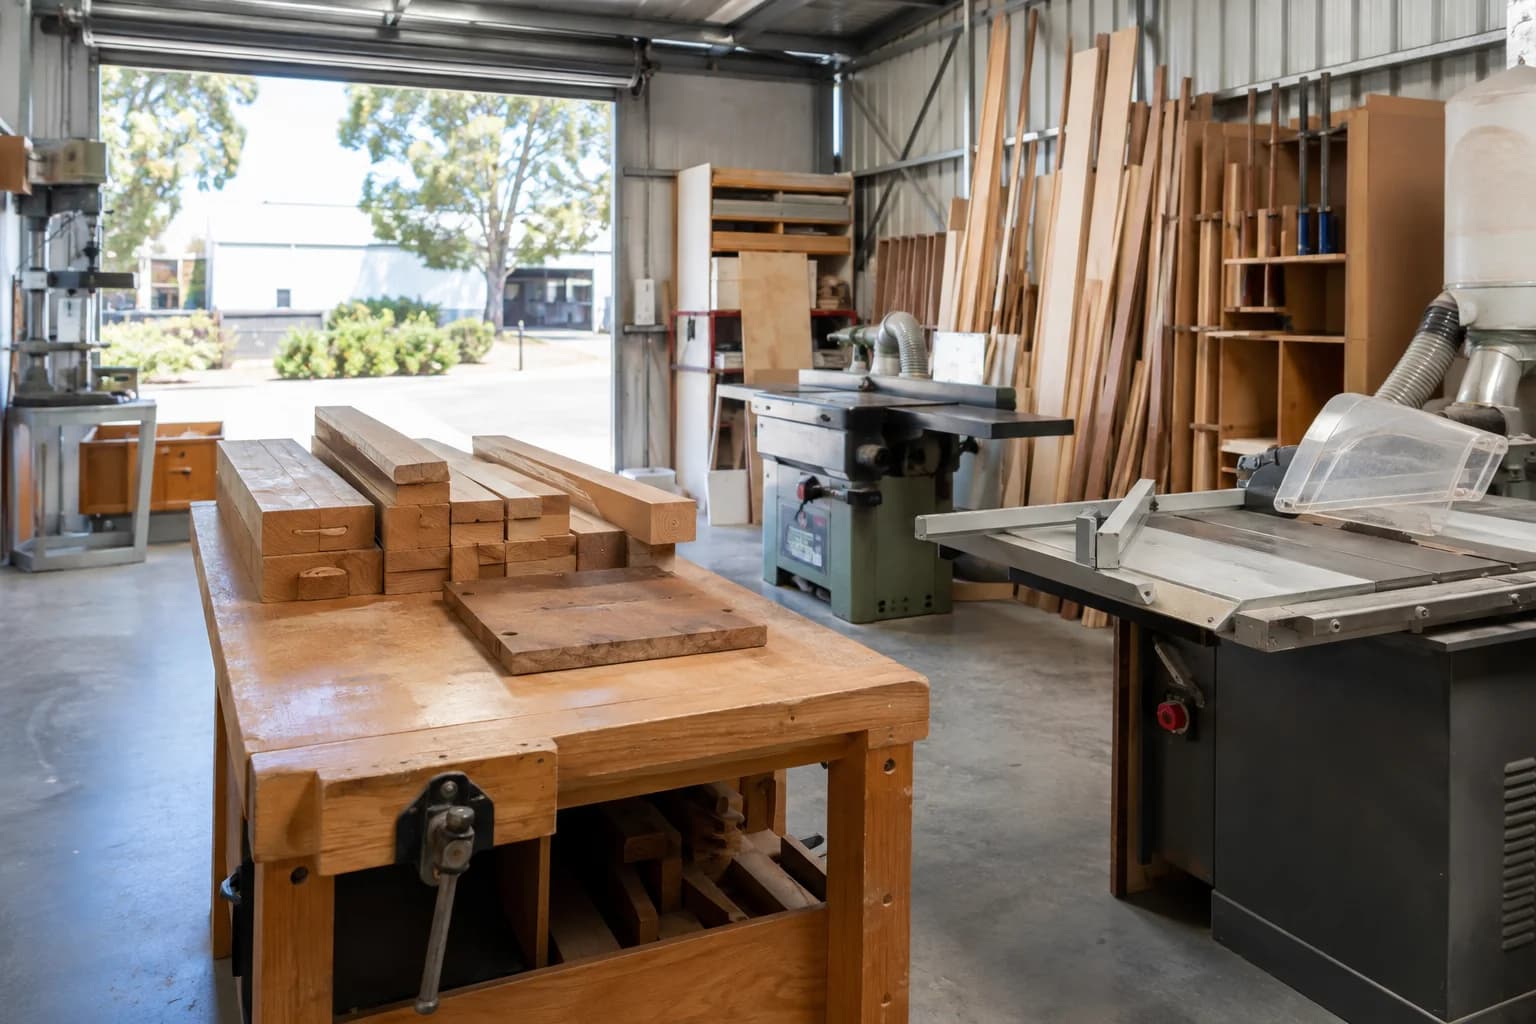
What can be financed
Most assets a business uses to earn its income.
- Vehicles, utes, vans and trucks, including trailers and fleet replacements.
- Earthmoving, agricultural, manufacturing and construction machinery.
- Fit-out, kitchen and refrigeration equipment for hospitality and retail.
- Medical, dental, veterinary and allied-health equipment.
- IT, software-heavy hardware and specialist equipment, where a lender has an appetite for it.
New, used, private-sale and imported assets are treated differently by lenders. Age, resale market and the seller all matter. We tell you early if an asset is one lenders find hard.
Choosing the structure
Chattel mortgage, finance lease or hire purchase.
The structure decides who owns the asset, when GST is claimed and how the cost is deducted. Your accountant confirms the tax treatment; we arrange the finance.
| Feature | Chattel mortgage | Finance lease | Hire purchase |
|---|---|---|---|
| Who owns the asset | You, from day one; the lender holds a mortgage over it | The lender; you rent it for the term | The lender until the final payment |
| GST | Usually claimable on the purchase price in the next BAS, if registered on an accruals basis | Paid on each rental and claimed as you go | Treated like a sale; ask your accountant |
| Deductions | Depreciation and interest | Rentals, to the extent of business use | Depreciation and the interest component |
| Balloon or residual | Optional, commonly 20 to 40 percent | Residual set by the lender | Optional |
| Term | 1 to 7 years | 1 to 5 years, typically | 1 to 7 years |
For passenger vehicles the ATO sets a car limit that caps depreciation and the GST credit; for the 2026-27 year the limit is $69,883 and the maximum GST credit is $6,353. Check the ATO page for the current year before you rely on it.
What lenders look at
The asset, the business, and the repayment history.
| Item | What to expect | What decides it |
|---|---|---|
| Deposit | Often none for standard assets; a contribution for older, specialised or private-sale assets | Asset type, age and resale market; time trading |
| Balloon | About 20 to 40 percent on vehicles and equipment | Asset life and your cash-flow preference |
| Term | 1 to 7 years | Asset life and the lender's policy |
| Low-doc threshold | Lender-specific amount below which financial statements are not required | Time trading, ABN and GST registration, property ownership, repayment history |
| Time to approval | Often days for low-doc under the threshold; longer with full financials or unusual assets | Lender, completeness of documents, valuation if required |
Low-doc is a lender policy, not a promise. It usually asks for an established ABN and GST registration, a clean repayment history and, for some lenders, property ownership. Above the threshold, expect to provide recent financial statements or BAS.
How it works
What we do for you, in four steps.
The same four steps for every business enquiry. We look at what repayments the business can afford, not only what a lender will approve.
- 01
Understand your business
Tell us what the finance is for, how much, when, who will borrow and how the business earns. We ask for documents only once we know which lenders fit.
- 02
Compare your options
We compare suitable lenders on total cost, structure and conditions, and explain the trade-offs in plain English. Waiting, or staying with your bank, can be the right answer.
- 03
Set the terms
The loan term, any lump sum at the end, the security, presales, progress payments and review dates are set to fit how the business earns and pays, not the lender's standard template.
- 04
Settle and follow through
We prepare the application, handle lender questions and valuations, and stay with you through settlement.
General information only. Any finance is subject to lender assessment and approval.
Questions people ask
Questions before you enquire
Do I need a deposit for equipment finance?
Often no, for standard assets with a clear resale market. Lenders may ask for a contribution for older, specialised or imported equipment, or where the business is newly trading. Your broker tells you which applies before an application.
Chattel mortgage, finance lease or hire purchase: which one?
It depends on who should own the asset, how you account for GST, and your tax position. Under a chattel mortgage the business owns the asset from day one and can usually claim the GST on the purchase price in the next BAS. Under a lease the lender owns it and GST is paid on each rental. Your accountant confirms the tax treatment for your situation.
What is a balloon payment?
A lump sum left at the end of the term to reduce the regular repayments. Balloons of about 20 to 40 percent of the asset price are common on vehicles and equipment over terms of one to seven years. A larger balloon lowers repayments but leaves more to refinance or pay out later.
Can I get equipment finance without full financials?
Yes, for smaller amounts. Some lenders lend up to a set amount on a signed declaration instead of financials (low-doc), for established businesses with a clean repayment history, subject to assessment. Above that amount, or for newer businesses, expect to provide financial statements or BAS. We tell you which path fits before you spend time on paperwork.
How long does equipment finance take?
Low-doc equipment finance under a lender's threshold is often approved within days once the quote and identification are in. Applications with full financials, or for unusual assets, take longer. Timing depends on the lender and the completeness of the documents, and is never a promise.
Does an enquiry affect my credit file?
No. Sending an enquiry does not authorise a credit check. Before any lender assessment, your broker explains what is checked, whether it is you or your company, and why.
Figures on this page were checked on 8 September 2026 against: ATO car limit and GST credit cap, Moneysmart business finance. Bands are typical market ranges and are not offers. Your lender, security and financials decide the actual terms.
All questionsWhen you are ready
Have a quote? Start there.
Send the supplier quote or the asset details with your enquiry and we will tell you which structure and lender fit, and what evidence they will want.