How to become a mortgage broker in Queensland
A clear path into mortgage broking.
The qualification, the memberships, the aggregator onboarding, the compliance training and the mentoring you need before you write your first loan, with what each one costs today.
Updated . General information only. Fees are set by each provider and change from time to time.
The pathway
Seven steps from study to your first settlement.
- 01
Certificate IV in Finance and Mortgage Broking
FNS40821 is the minimum qualification for a mortgage broker under ASIC Regulatory Guide 206. We recommend Kaplan Professional.
- 02
Choose an aggregator
The aggregator holds the Australian Credit Licence you work under, and gives you lender access, software and compliance support.
- 03
Join AFCA
Every credit representative must belong to the Australian Financial Complaints Authority before they can be authorised.
- 04
Credit representative appointment
Your aggregator authorises you under its licence and registers you with ASIC. You receive your credit representative number.
- 05
Aggregator onboarding and compliance training
You attend a broker onboarding session with your aggregator, set up its systems and complete its compliance training, including anti-money laundering (AML) training and the tools you use to verify each client. At Chorus, this is AFG.
- 06
Join the FBAA
Industry membership brings the code of practice, professional development and the standing most lenders expect.
- 07
Mentoring and the Diploma
You write your first loans under a mentor, and complete the Diploma of Finance and Mortgage Broking Management (FNS50322).
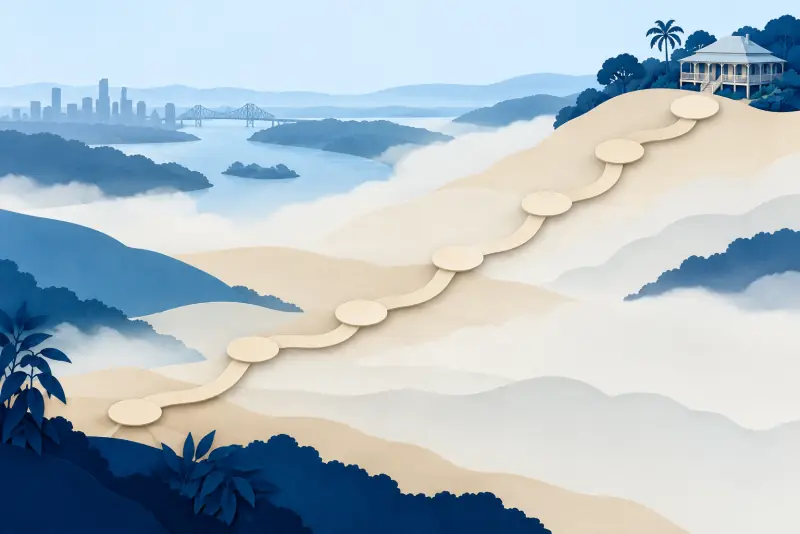
Journey map
From study to your first settlement, at a glance.
- 01
Certificate IV
Kaplan, $380
- 02
Aggregator
Apply and be accepted
- 03
AFCA
$73.01 a year
- 04
Appointment
Credit representative number
- 05
AFG onboarding
Compliance and AML training
- 06
FBAA
$440 a year + $125
- 07
First year
Mentoring and the Diploma
What it costs
About $1,020 before aggregator fees.
Published prices at September 2026. Check with each provider before you pay.
| Item | Cost | Notes |
|---|---|---|
| Certificate IV, Kaplan Professional | $380 | FNS40821. GST exempt, paid upfront, studied online. |
| FBAA membership, new to industry | $440 a year | Plus a one-off $125 application fee. Moves to $565 a year after two years. |
| AFCA membership | $73.01 a year | Annual registration fee for an authorised credit representative, 2026–27 year. Complaint fees apply only if a complaint about you proceeds. |
| Diploma upgrade, Kaplan Professional | $380 | FNS50322 upgrade for Certificate IV holders. The full Diploma is $750. |
| Aggregator | Varies | A share of your commission, a monthly fee, or both. Ask each aggregator for its full fee schedule. |
| First-year total for the Certificate IV, FBAA and AFCA: $1,018.01. Add the Diploma, aggregator fees and your own costs such as software, marketing and a vehicle. | ||
Questions
What people ask before they start.
Certificate IV with Kaplan
The qualification
What qualification do I need to become a mortgage broker?
The minimum is the FNS40821 Certificate IV in Finance and Mortgage Broking. ASIC sets this standard in Regulatory Guide 206. Aggregators and lenders will ask for your certificate before they accredit you.
How much does the Certificate IV cost with Kaplan?
Kaplan Professional lists the Certificate IV at $380, GST exempt, paid upfront. Kaplan sets its own fees, so confirm the price on the Kaplan course page when you enrol.
Why Kaplan?
Kaplan Professional is a long-established provider in financial services education. The course is online and self-paced, and it leads straight into the Kaplan Diploma upgrade. Other registered training organisations offer the same qualification, and any of them meets the ASIC standard.
Do I also need the Diploma?
The Certificate IV lets you start. Most aggregators, and the MFAA, expect you to complete the FNS50322 Diploma of Finance and Mortgage Broking Management, usually within your first year. Kaplan's Diploma upgrade for Certificate IV holders is $380. The full Diploma is $750.
FBAA membership
Your industry association
What is the FBAA?
The Finance Brokers Association of Australia is one of the two industry associations for brokers. The other is the MFAA. Members agree to a code of practice, complete professional development each year and have access to a complaints and standards process.
Do I have to join?
The law does not require it. In practice most aggregators and lenders expect you to belong to the FBAA or the MFAA before they accredit you. The FBAA accepts the Certificate IV for entry, so you can join before you finish the Diploma.
How much does FBAA membership cost?
- New to industry: $440 a year, plus a one-off $125 application fee. This rate is for brokers with less than two years in the industry, nominated by a current FBAA member.
- Standard broker: $565 a year, plus the $125 application fee if you are new to the FBAA.
See the current rates on the FBAA membership page.
AFCA membership
External dispute resolution
What is AFCA and why do I need it?
The Australian Financial Complaints Authority is the free, independent complaints scheme for financial services. The National Consumer Credit Protection Act requires every credit licensee and every credit representative to be a member. Your aggregator cannot authorise you until you have an AFCA membership number.
How much does AFCA cost?
For the year from 1 July 2026 to 30 June 2027, the annual registration fee is $73.01 for an authorised credit representative. A credit licensee pays $415.57. AFCA charges further fees only when a complaint about you is lodged and proceeds past the early stages.
See the AFCA membership page to apply.
When do I apply?
Apply after your aggregator accepts you and before it authorises you. The aggregator needs your AFCA number to complete your appointment with ASIC. Membership renews each July.
Joining an aggregator
Your licence and lender access
What does an aggregator do?
An aggregator sits between you and the lenders. Most new brokers work under an aggregator's licence rather than holding their own. The aggregator:
- holds the Australian Credit Licence and authorises you as a credit representative under it
- gives you accreditation with its panel of lenders
- supplies loan comparison, lodgement and client management software
- sets compliance standards, audits your files and usually arranges professional indemnity cover
- receives your commission from the lender and pays you your share
- runs training and gives you access to lender business development managers
How is the aggregator paid?
Aggregators take a share of the upfront and trail commission, charge a flat monthly fee, or combine the two. A higher split usually comes with a monthly fee. Ask each aggregator for its full fee schedule, including software, professional indemnity and compliance costs, before you sign.
Which aggregator does Chorus use?
Chorus Finance is a credit representative of AFG (Australian Finance Group, Australian Credit Licence 389087). You are free to choose any aggregator. We can talk through how AFG works day to day if it helps your decision.
What does the aggregator ask for when I apply?
Expect to provide your Certificate IV, identification, a national police check, a credit check and details of your background. Some aggregators also ask for a mentoring arrangement before they appoint a new broker.
Onboarding and compliance with AFG
Before your first client
What happens at the AFG broker onboarding session?
After AFG appoints you, you attend a broker onboarding session. AFG sets up your access to its lodgement and client management systems, explains how commission is paid to you, and takes you through its compliance standards and file requirements. You also start the accreditation process with the lenders on AFG's panel.
What compliance training do I complete?
AFG gives you a set of compliance training modules to complete before you see clients, then refresher training each year. The modules cover your obligations as a credit representative, including responsible lending, best interests duty, privacy, complaints handling and anti-money laundering.
What is the AML tooling and why do I need it?
Anti-money laundering and counter-terrorism financing (AML/CTF) law requires lenders to know who their customers are. As the broker, you verify each client's identity and collect the information the lender needs. AFG gives you the AML training and the verification tools you use to do this on every file, and keeps a record of each check.
Is there a cost for AFG onboarding and training?
Ask AFG for its current fee schedule when you apply. It sets out what is included in onboarding, training, software and professional indemnity cover.
Mentoring with Chorus
Your first year
Why do new brokers need a mentor?
Aggregators, lenders and the industry associations usually expect a new broker to work under an experienced mentor for their first 12 months. The mentor reviews your files, answers policy and compliance questions, and confirms your progress to your aggregator.
How does mentoring with Chorus work?
- A first conversation. We talk about your background, the clients you want to serve and where you are in the pathway.
- A written agreement. Before we start, we agree in writing the scope, the time commitment, any fee and how file reviews work.
- Shadowing. You sit in on client interviews and follow real files from the first call to settlement.
- File review. We review your files before they go to a lender, until you and your aggregator are ready for you to submit on your own.
- Regular check-ins. We meet on a set schedule to go through your pipeline, lender policy and compliance.
- Sign-off. At the end of the period we confirm your progress in writing to your aggregator.
Is there a fee for mentoring?
Any fee depends on the scope we agree. We set it out in writing before we start.
Do I need to use AFG to be mentored by Chorus?
Tell us which aggregator you plan to use when we first speak. Some aggregators have their own rules on who can mentor their brokers, and we check that before we agree anything.
Broking with Chorus Finance
Apply to join Chorus.
From our Brisbane practice, we mentor a small number of new brokers through their first year. If you want to build a practice around advice and long client relationships, tell us about yourself.
- 01
Send your application
Your background, where you are in the pathway and the clients you want to serve.
- 02
A first conversation
We talk about how Chorus works, how you like to work and whether the fit is right on both sides.
- 03
Time with the team
You sit in on client meetings and see how a Chorus file runs from the first call to settlement.
- 04
A written agreement
We agree the arrangement, the mentoring scope and any fee in writing before you start.
- 05
Onboarding with AFG
Your appointment, the AFG onboarding session, compliance and AML training, then your first clients with us beside you.
Thinking about broking
Tell us where you are in the pathway.
Whether you have not started the Certificate IV or you are choosing an aggregator, we are happy to talk it through.